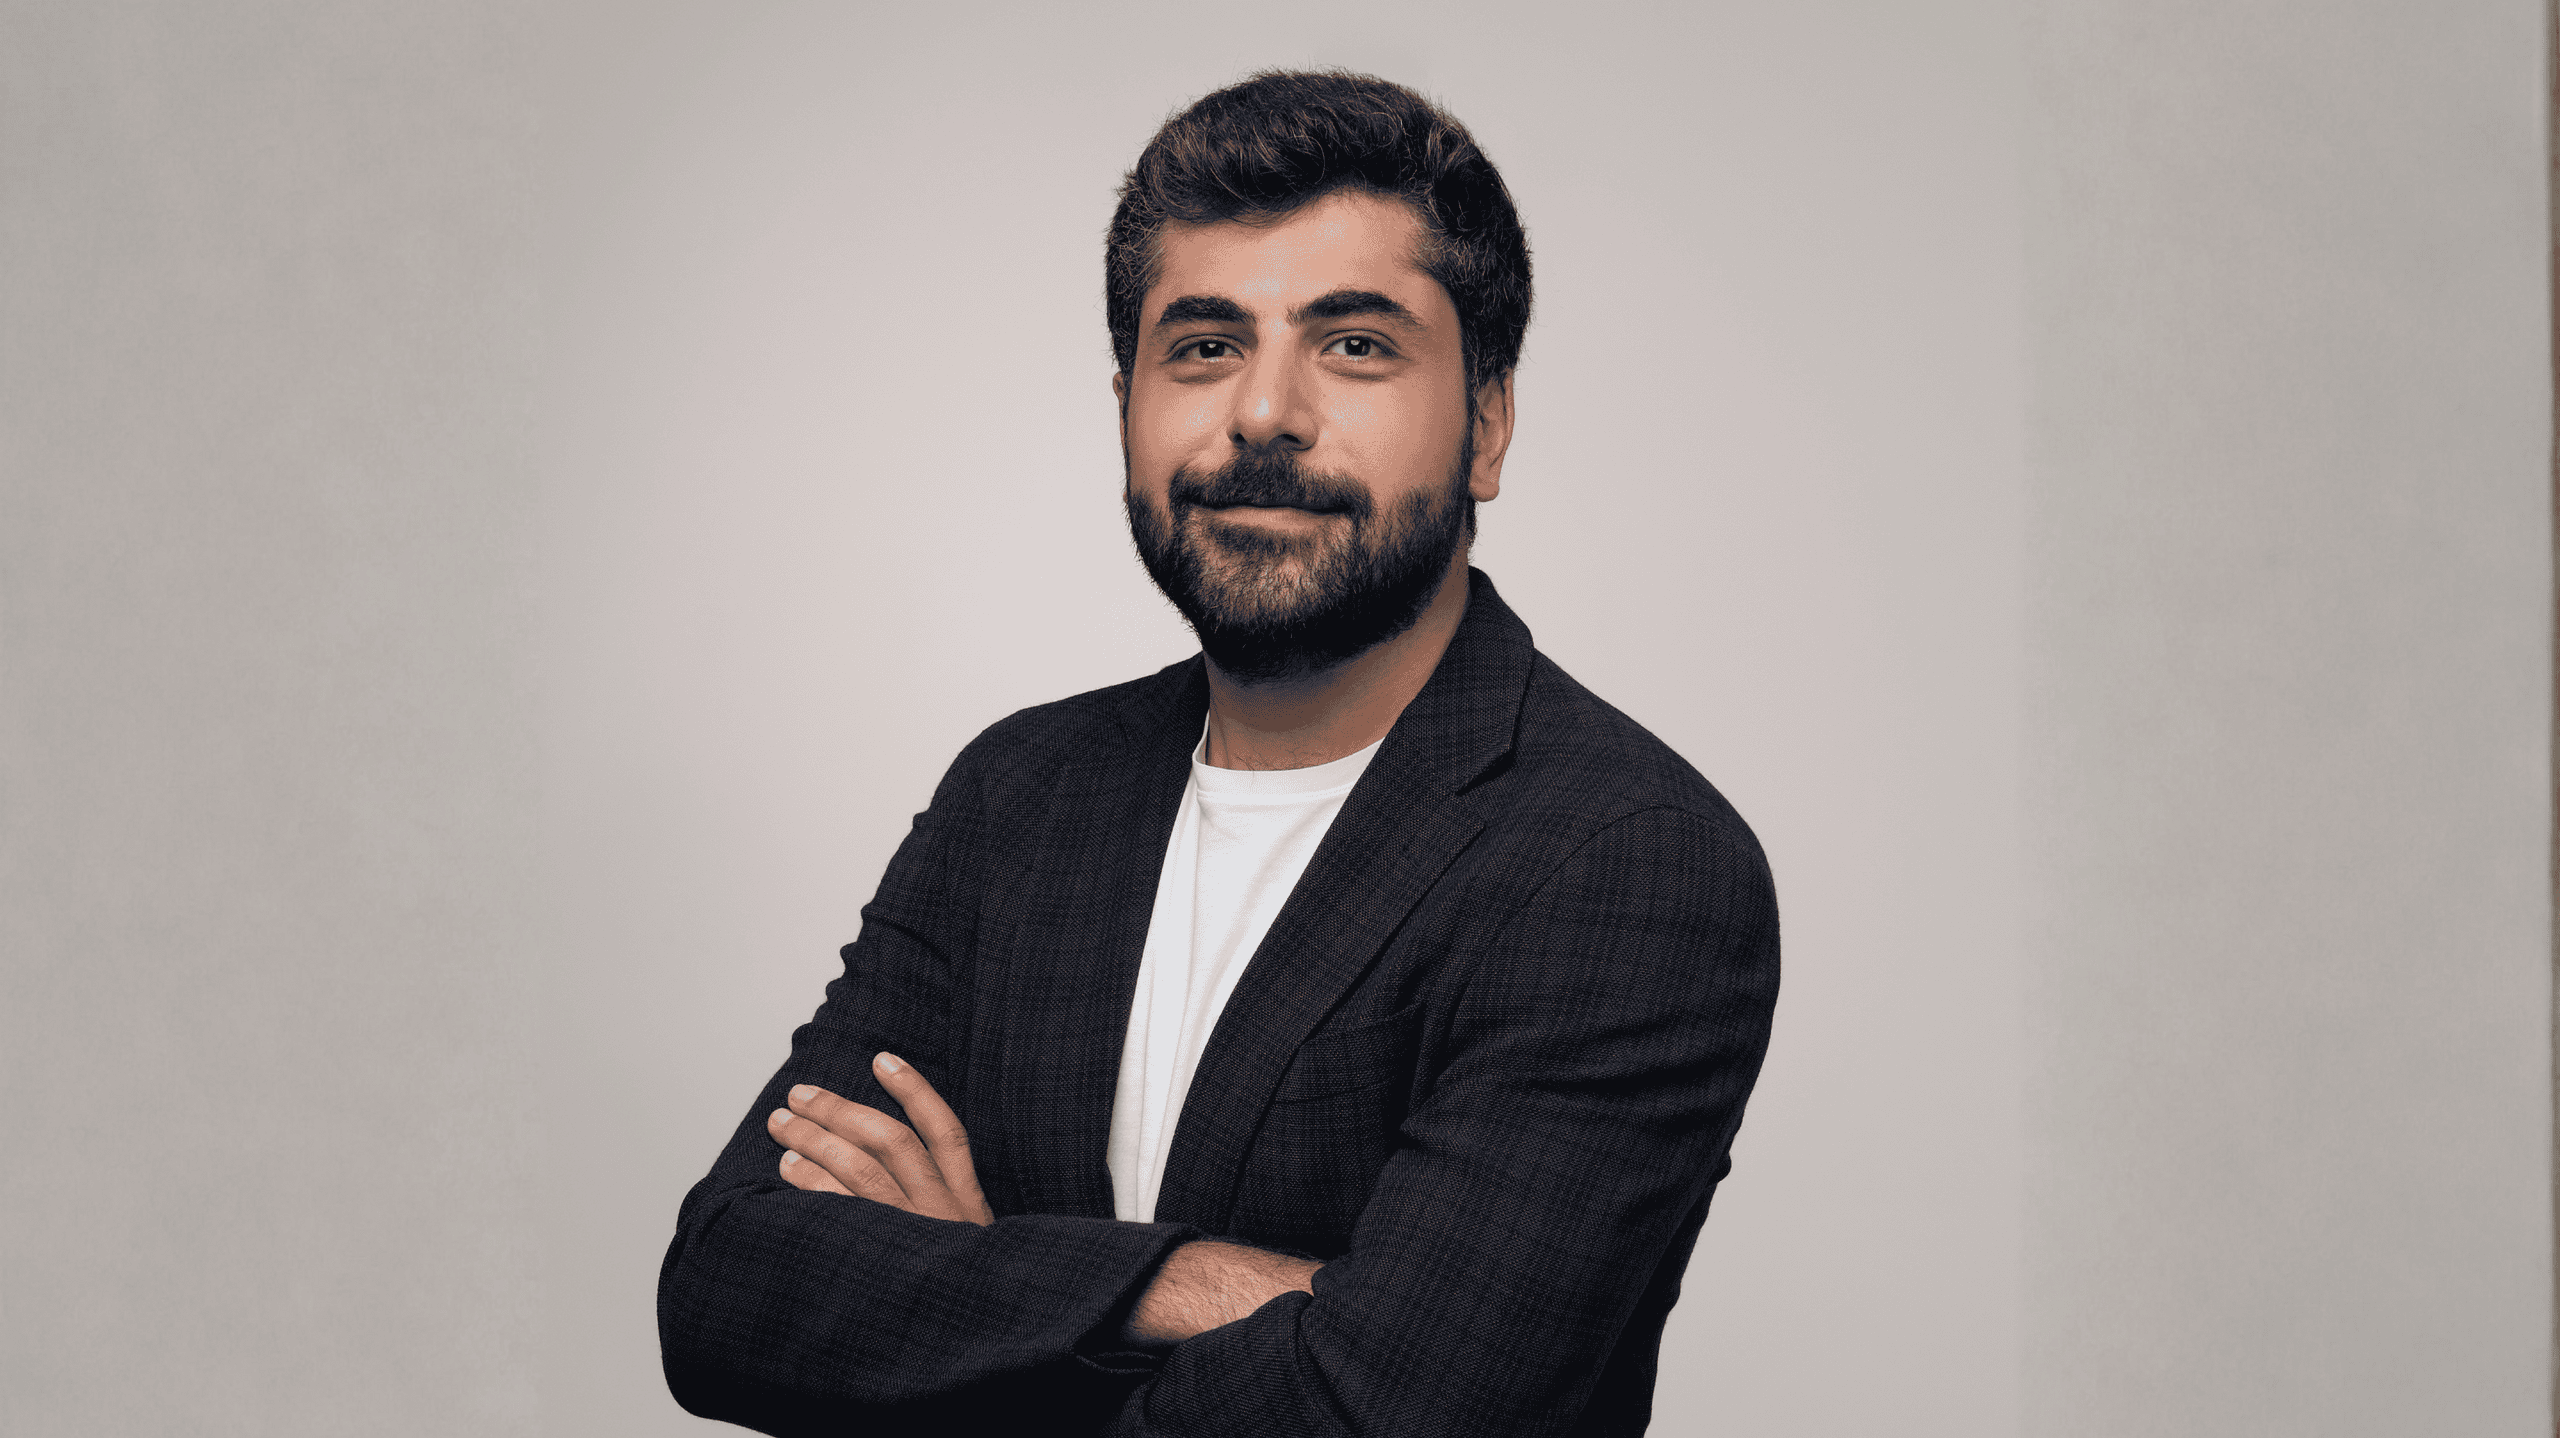


Giorgi Vakhtangishvili, chief digital officer at Bank of Georgia, shares his thoughts on super-apps, AI financial agents, and frictionless security.
Global Finance: Bank of Georgia takes nine awards in our 2026 World’s Best Digital Banks. What core technological or cultural shift drove your performance across those categories?
Giorgi Vakhtangishvili: It wasn’t one feature, it was a shift to building customercentric, AI-native infrastructure that removes decision friction. The proof: 95% of our unsecured loans are automated and AI-enhanced, approved and disbursed in under 15 seconds. Meanwhile, 53% of users open the app daily, an engagement rate most social media platforms would envy from a banking app.
Additionally, our embedded generative AI assistant resolves over 78% of customer queries without human intervention, maintaining a 91% satisfaction score. That combination — instant decisions, daily habit, and AI that customers actually trust — is the real catalyst. Consistency across nine categories reflects consistency across that entire stack.
GF: In a country that already has high digital adoption, is Bank of Georgia expanding its mobile platform into lifestyle and embedded services to deepen engagement?
Vakhtangishvili: We think of the app as a financial super-app rather than a banking app, one designed to accelerate core banking while making it more contextual to daily life. A few examples: Home Space consolidates property-related finances—utilities, bill reminders, direct debits—in one hub; Car Space does the same for vehicle ownership, from insurance to getting notified of a police fine and paying it in one tap. A citizen can pay their taxes, pull their National Revenue Service records, and pay 30-plus state services, all without leaving our app.
On the investing side, any user can open an investment account in under a minute, buy a fractional share of a New York Stock Exchange-listed stock for $1, and trade 100-plus cryptocurrencies on the same screen they use to pay their electricity bill. And we’re building tomorrow’s customers today; 188,000 schoolchildren use our financial literacy app every month, learning to save before they’ve ever earned a salary. That’s the model: depth of relationship, not breadth of separate apps.
GF: As retail digital banking evolves, do you see the primary consumer interface shifting away from traditional app dashboards toward autonomous, AI-driven financial agents?
Vakhtangishvili: Directionally, yes, and we’re already living part of that future. When 95% of unsecured lending decisions and disbursals happen automatically in under 15 seconds and our AI assistant independently resolves almost 80% of customer queries at 91% satisfaction, the “agent” is already doing the work; the dashboard is increasingly just the visible tip of a much more autonomous system underneath.
That will go further. AI won’t just power decisions behind the scenes, it will start generating the interface itself, assembling around what a customer needs in the moment rather than a static screen customers navigate.
But I’d draw a clear line at reversibility. Routine, low-stakes actions can run fully on the agent; that’s already happening. Anything irreversible or above a customer’s own threshold—a large transfer, a new credit line, an investment trade—stays one tap from a human decision, because in banking, trust is the product, not a feature.
GF: As experiences become frictionless and instant, do digital banks need to rethink security and consumer trust against emerging fraud vectors?
Vakhtangishvili: The instinct is to see speed and security as opposing forces, but we’ve found the opposite is true when trust is engineered into the rails themselves.
A business used to wait several business days for a bank guarantee to bid on a government tender. But by integrating directly with Georgia’s state procurement agency, we cut that to under an hour: a complex, high-stakes financial instrument made instant without cutting a single compliance corner. That’s paired with biometric liveness detection at onboarding and machine-learning fraud detection, continuously recalibrating against new fraud patterns.
The principle: the more invisible we make banking for the customer, the more rigorous—and more visible internally—our risk controls need to be.