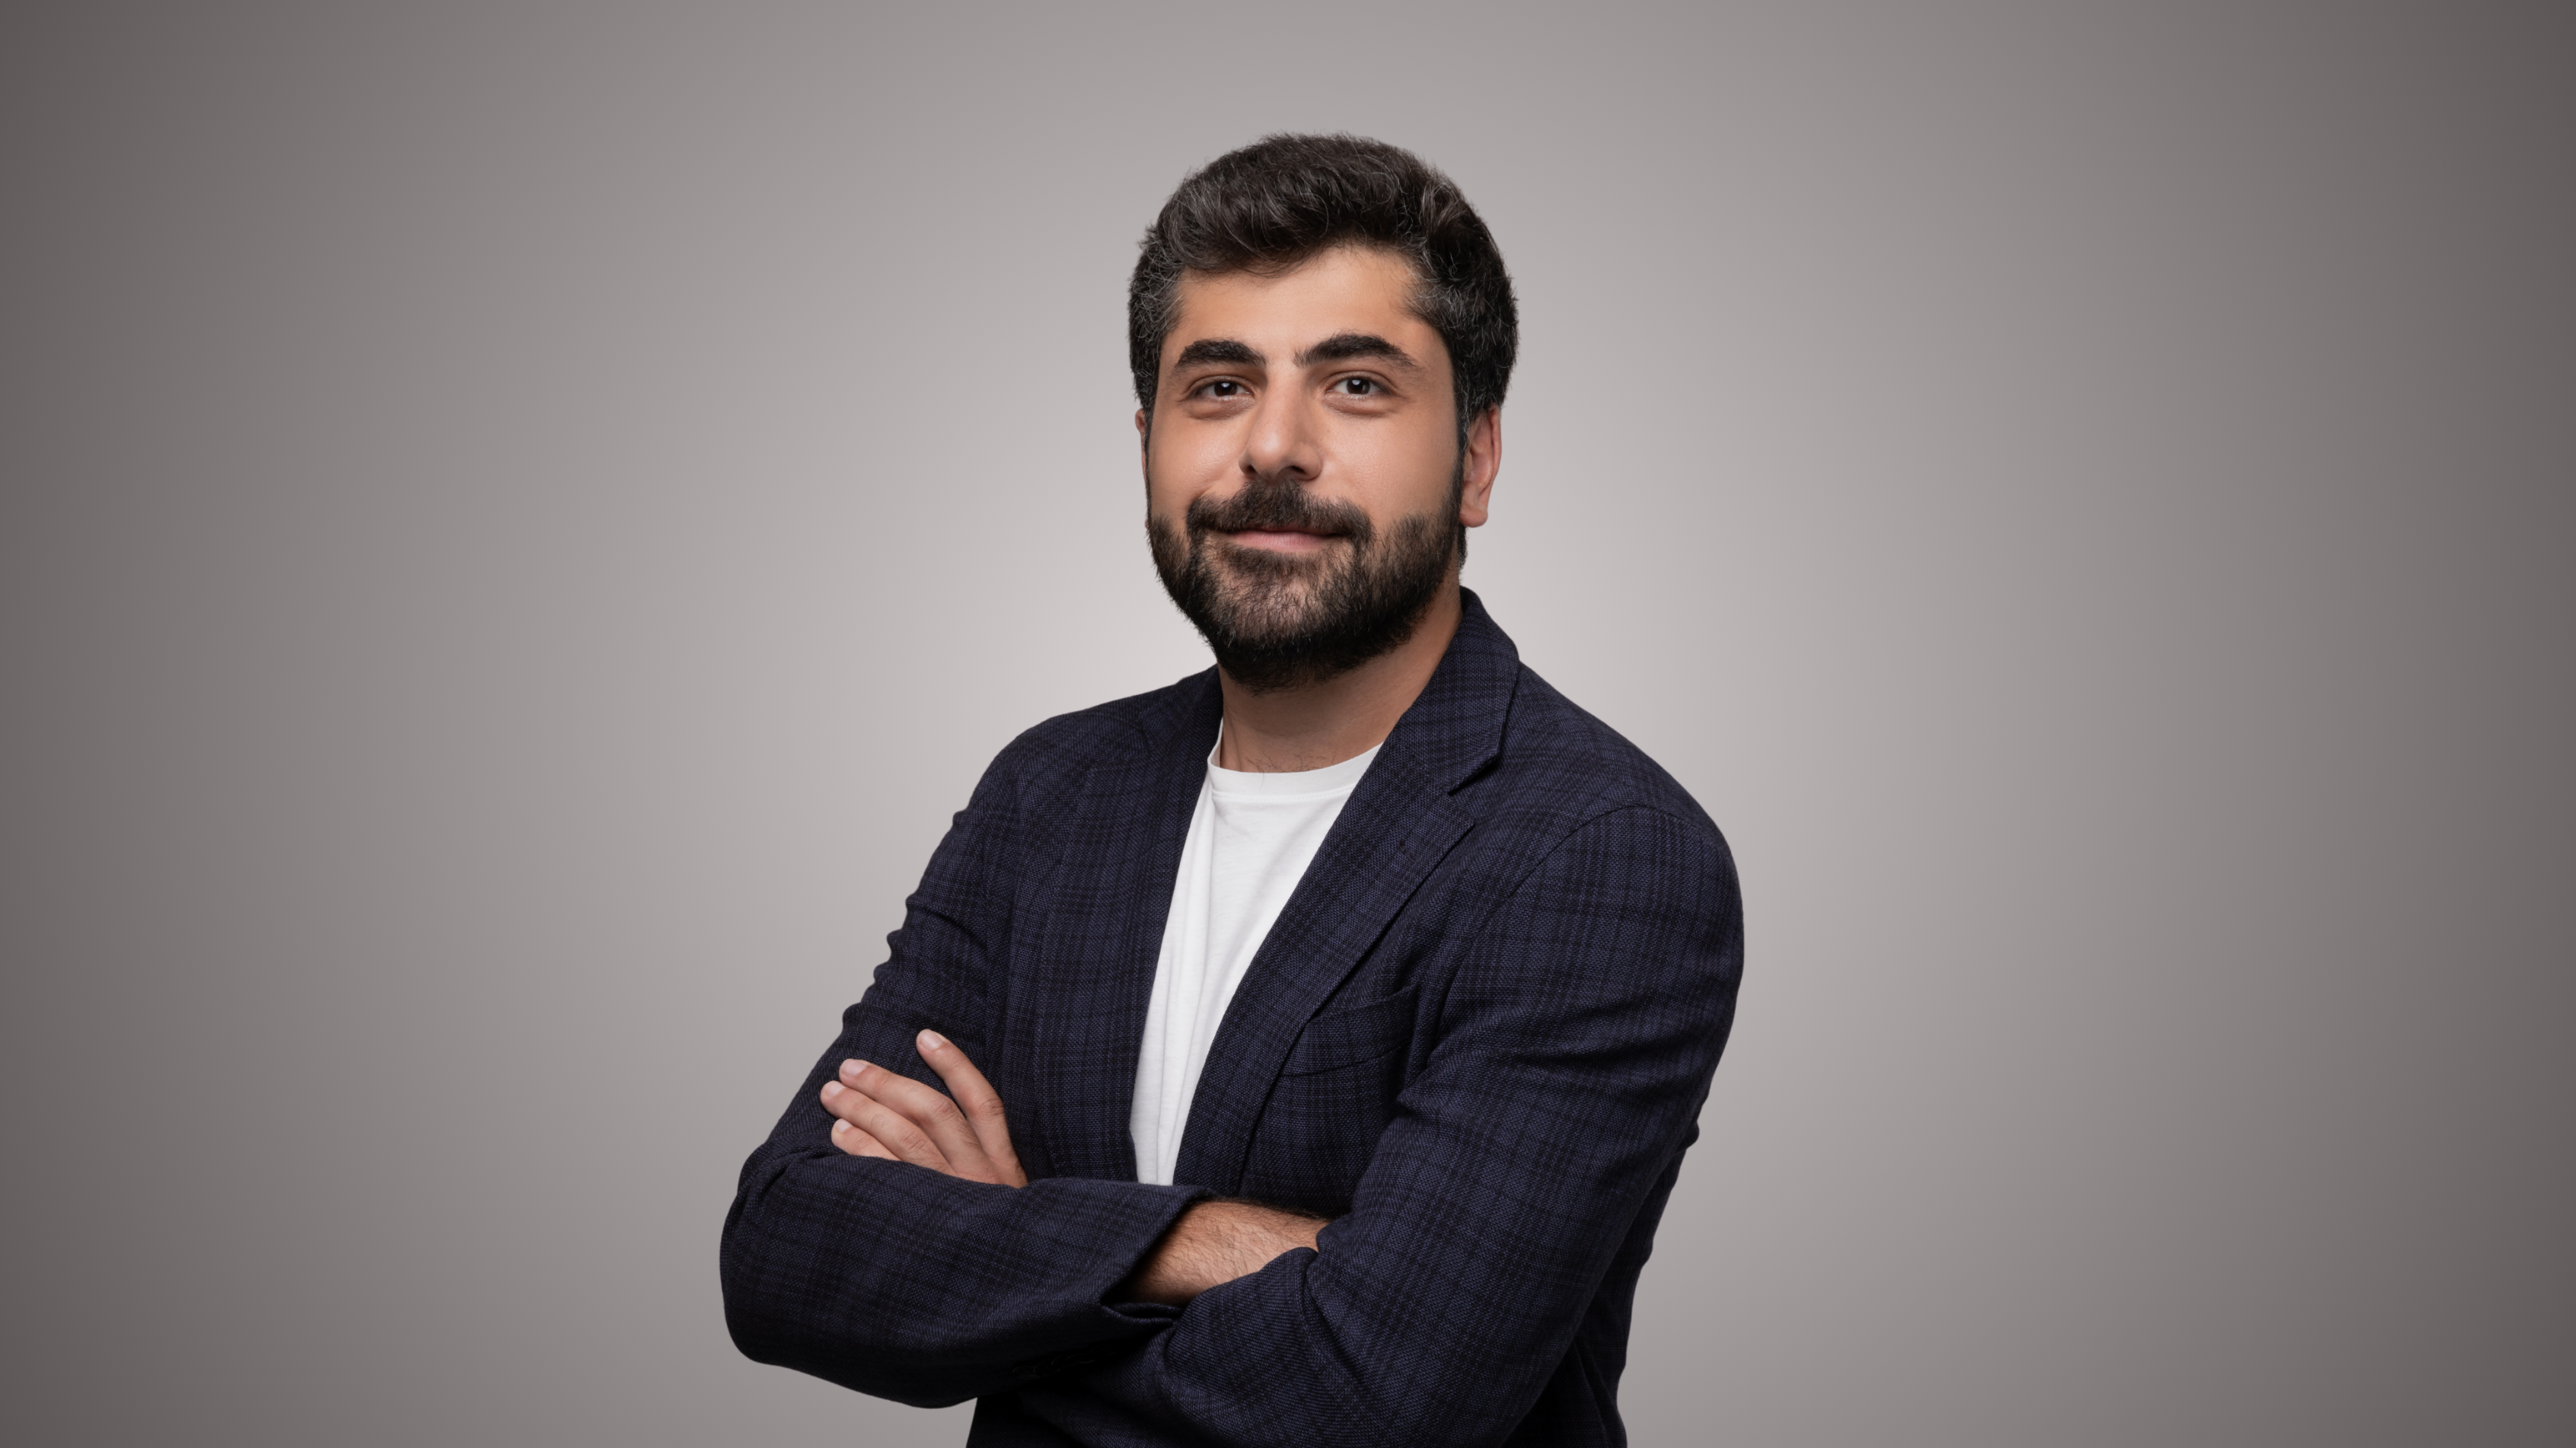


Mark Monaco, head of Global Payments Solutions at Bank of America, which won a Most Innovative Digital Bank award, explains how to build digital speed and resilience through integrated payment solutions and real-time insights.
Global Finance: How can global banks integrate fragmented regional instantpayment systems without imposing additional technical burdens on treasurers as the G20’s 2027 deadlines approach?
Mark Monaco: The challenge is connecting payment rails in a simple and scalable way. Corporate treasurers don’t want to manage a patchwork of domestic schemes market by market. They need banking partners to absorb that complexity. Our cross-border, real-time payment capability helps clients move high-volume, low-value flows efficiently with real-time tracking and local-currency settlement. This gives clients the flexibility to use high-velocity domestic payout options while benefiting from a centralized treasury approach. Our goal is to expand payment options while reducing operational friction.
We also support industrywide efforts and collaborate with market infrastructures to address these challenges. As new frameworks take hold, BofA uses its global scale to advance G20 goals and enable seamless cross-border movement of money.
GF: CashPro Forecasting has automated what used to be a weeklong manual spreadsheet process, reducing it to minutes. How is IT altering how CFOs calculate and manage their daily liquidity cushions?
Monaco: Immediate forecasting shifts the focus from backward-looking reporting to forward-looking liquidity management. When treasurers can generate forecasts in minutes rather than days, they gain a more current view of their cash position. This precision allows CFOs to reduce overly conservative liquidity buffers without sacrificing resilience. They can respond faster to market shifts, trade dynamics, and business events. Better forecasting transforms liquidity into a strategic resource. Within our CashPro platform, client adoption of this tool is up 25% year over year, with approximately 3,500 clients currently using the solution.
GF: How is BofA leveraging its CashPro Data Intelligence strategy to turn transaction data into proactive defenses against modern AI-driven fraud and cyber threats?
Monaco: Data intelligence allows us to move beyond simple transaction reporting to identifying patterns and anomalies early. For treasurers, this means using data to strengthen controls and improve payment choices. Our CashPro Data Intelligence suite embeds these insights directly into the workflow, highlighting opportunities for efficiency and fraud protection. We are moving from static dashboards to proactive models where data provides practical signals for faster decision-making. In a sophisticatedthreat environment, monitoring anomalies across segments is a key differentiator. We utilize cutting-edge cybersecurity and network management to monitor both inbound and outbound payment requests.
GF: CashPro Capital Markets Insights embeds bond market data directly into the treasury dashboard. Why has it taken so long to integrate transaction banking with debt intelligence?
Monaco: Historically, treasury management and debt-market intelligence were separate workflows. Technology now allows us to consolidate bond-market data, issuance activity, and pricing directly into the treasury platforms that teams use daily. Our AI-driven Trade Evaluation Driver score translates market variables into clear signals about issuance conditions, helping clients evaluate the macro backdrop objectively. By digitizing this information, we have reduced friction and provided decision-makers with more confidence when assessing market windows.
GF: How are you helping corporates optimize working capital while protecting their broader supplier ecosystems?
Monaco: Working capital optimization and supplier resiliency are now inseparable. Our API-first architecture allows treasury and [enterprise resource planning] environments to connect seamlessly, embedding payments into existing processes with speed and control. Our payables capabilities help clients digitize invoices and expand electronic-payment adoption. This creates a twofold value proposition: Buyers manage working capital more intelligently, while suppliers benefit from faster, predictable payment experiences. Resiliency comes from creating a payables model that serves the entire network, not just the payer.