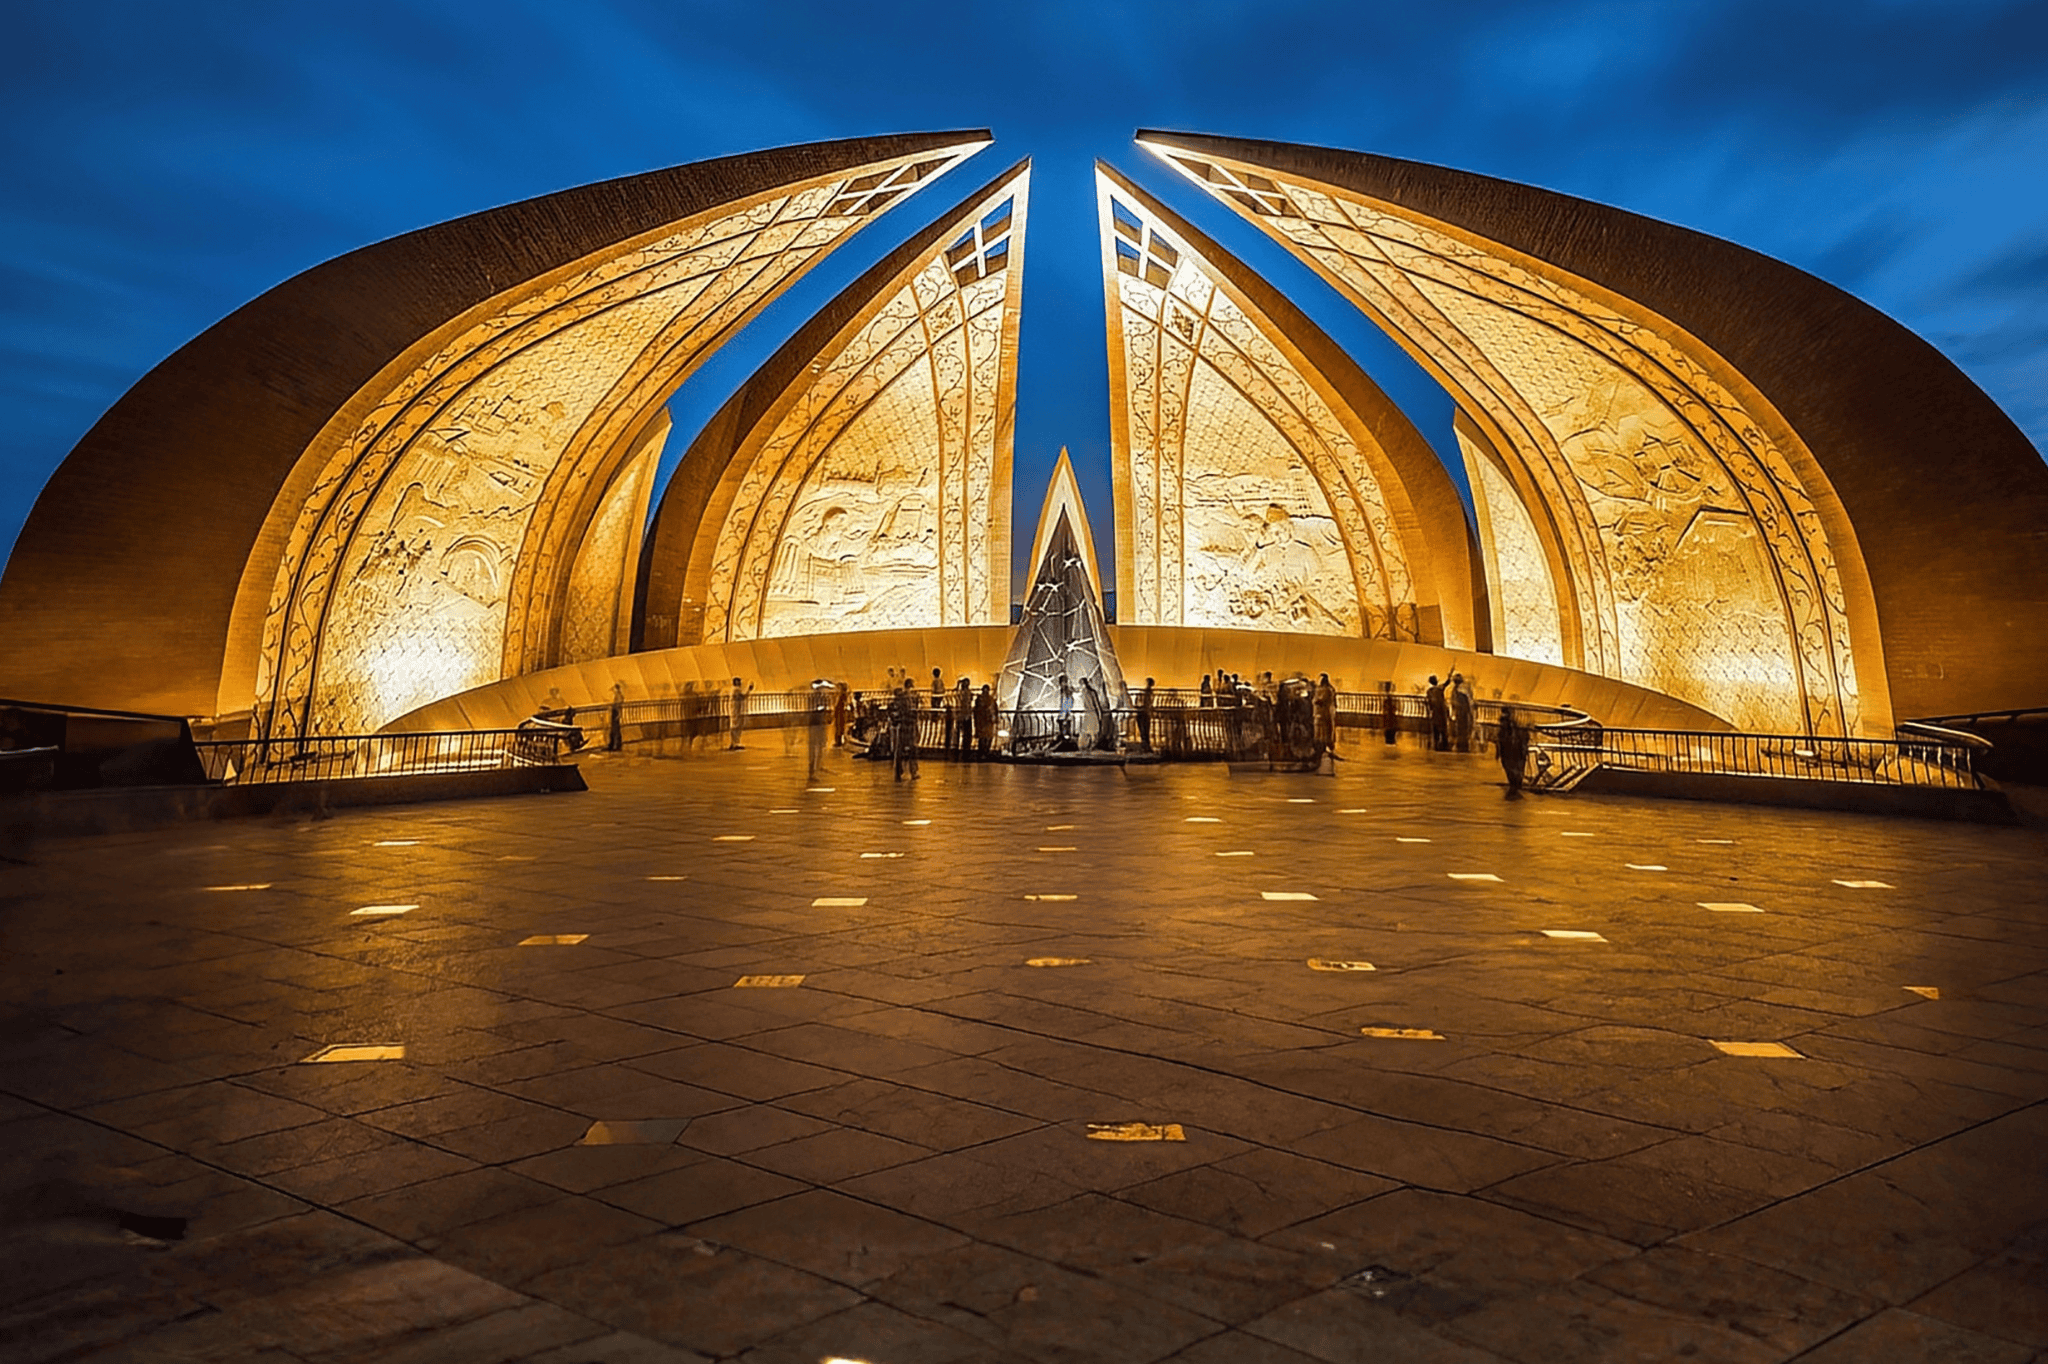


Emergency financing and debt rollovers have given Islamabad crucial breathing room for growth.
This article appears in the October issue of Global Finance Magazine.
Pakistan’s economy has staged a comeback from the brink of sovereign default. Three catastrophic events in 2022 exacerbated its existing fiscal and external vulnerabilities: the Russia–Ukraine war, the political instability after the ouster of Imran Khan’s Pakistan Tehreek-e-Insaf government, and floods that submerged a third of the country.
According to a World Bank-led assessment, the floods caused more than $30 billion in damages and economic losses, reducing fiscal year 2022 gross domestic product by an estimated 2.2%.
Subsequently, foreign-exchange reserves fell to around $4.2 billion in March 2023 from $9.8 billion at the end of June 2022 — equivalent to roughly one month of imports, due to large external debt repayments and higher outflows. Finally, headline inflation reached a record 38% in May 2023, up from 13.8% in May 2022.
The Pakistani government needed emergency financing, and China rolled over and refinanced almost $7 billion that Pakistan was due to repay between January and June 2023, playing a pivotal role in easing immediate financing pressures.
The International Monetary Fund approved a $3 billion nine-month Stand-By Arrangement in July of 2023. It was backed by politically painful measures: tax hikes, subsidy reversals, a market-based rupee, and spending cuts.
After the IMF approved the arrangement, Saudi Arabia and the United Arab Emirates contributed $2 billion and $1 billion, respectively.
Then, in September 2024, the IMF approved a $7 billion Extended Fund Facility, extending the rescue into a 37-month program.
| Vital Statistics |
|---|
| Location: Located in the northwestern part of the South Asian subcontinent |
| Neighbors: Iran, Afghanistan, China, and India |
| Capital city: Islamabad |
| Population (2025): 255.2 million |
| Official language(s): Urdu (National Language) and English used for official purposes |
| GDP per capita (Calendar Year 2025): $1,595.9 (current); $6,573.40 (PPP Current International) |
| GDP size (Calendar year 2025): $407.31 billion (Current) |
| Real GDP growth: FY2025: 3.1% (actual); FY2026: 3.5% (forecast); FY2027: 4.5% (forecast) |
| Inflation [calendar year 2025]: 3.5% |
| Unemployment rate: 5.4% (2025, International Labour Organization modelled estimate) |
| Currency: Pakistani Rupee |
| Credit rating: B3 Stable Outlook (Moody’s Global Ratings), B- Stable Outlook (Fitch Ratings), B Stable Outlook (S&P Global Ratings) |
| Investment promotion agency: Board of Investment Pakistan |
| Investment incentives available: Up to 100% foreign ownership, subject to sector-specific restrictions, no minimum foreign-investment requirement, repatriation of profits and dividends subject to applicable foreign exchange regulations, a 10-year income tax exemption for qualifying Special Economic Zone enterprises, first residency-by-investment scheme introduced under the Foreigners (Long Term Residency) Order, 2025, and foreign investors can acquire/lease land subject to applicable laws |
| Corruption Perceptions Index rank [2025]: 136 out of 182 countries, according to Transparency International |
| Political risk: Political instability and polarization, Policy and regulatory uncertainty, Limitation of enforcing contracts and protecting property rights, corruption, IMF dependence and policy continuation risk, recurring India-Pakistan conflicts, Afghanistan-Pakistan conflicts, and civil-military tensions |
| Security risk: Terrorism and militant violence: attacks on employees or assets leading to higher security costs or project delays, higher insurance costs, and lower expected returns. Geographically exposed projects like energy, mining, transport, ports, and large infrastructure are usually affected |
Headwinds Linger
While Pakistan’s macroeconomic position has improved, the economy is vulnerable to two major geopolitical headwinds.
First, the Middle East conflict threatens the country’s external stability through higher oil prices, increased shipping costs, and potential reductions in Gulf-based remittances.
Second, the deteriorating security relationship with Afghanistan is disrupting bilateral trade, increasing security expenditure, and undermining Pakistan’s ambition to become a gateway to Central Asia.
Beyond geopolitical risks, Pakistan faces several structural challenges, including attracting foreign direct investment, diversifying exports, and reducing its reliance on China for external financing.
The security issues are particularly significant at a time when the government is actively promoting FDI in mining.
A case in point is the Canadian-based Barrick Mining Corp., which owns a 50% stake in Pakistan’s Reko Diq project. It slowed development and extended its security review amid concerns over the deteriorating security situation.
Similarly, insurgent violence disrupted the supply routes of the Chinese-operated Saindak copper and gold mine in Balochistan, prompting the Pakistani government to provide additional security assurances.
Financing by multilateral agencies further underscores the project’s strategic and economic importance. The International Finance Corp. approved a $700 million loan to Reko Diq in June 2025, and the Asian Development Bank (ADB) approved up to $410 million in August 2025.
According to ADB, the investments by all entities in Reko Diq will make it the largest foreign direct investment in Pakistan’s history.
When fully operational, Reko Diq is expected to become the world’s fifth-largest copper mine and help address the projected global copper shortage. Thar Coal and Duddar are other major mining sites.
Green Shoots Appear
The economy started showing signs of recovery in 2025. Pakistan became top-ranked in Bloomberg Intelligence’s Global Emerging Markets ranking for credit risk improvement in 2025. It recorded the steepest decline in sovereign default risk (59% to 47%) in 2024, eclipsing major emerging markets like Argentina (-7%), Tunisia (-4%), and Nigeria (-5%).
| CONS |
|---|
| Energy and infrastructure constraints: weak electricity transmission and distribution infrastructure, circular debt, dependence on imported energy, expensive electricity, leading to lower growth, pressure on inflation and foreign exchange, and higher cost of doing business. |
| In Germanwatch’s long-term Climate Risk Index 2026, Pakistan is ranked 15th among the countries most affected by extreme weather events over the 30 years from 1995 to 2024. |
| The country hosts around 1.6 million Afghan refugees and asylum seekers. |
Pakistan’s macro indicators strengthened in fiscal 2026: GDP growth was 3.7%, the fastest growth in four years, driven by a recovery in the industrial sector and a surge in the automobile and textile sectors.
Information and Communication Technology (ICT) was the top performer, growing 7.5%. Inflation fell sharply to an average of 6.2% in the July to April period of fiscal 2026.
The IMF’s third review in May 2026 also found strong reform implementation, with improved GDP growth and progress in stabilizing the economy.
| PROS |
|---|
| More than 300,000 English-speaking, IT and IT-enabled service professionals. |
| Double Taxation Treaties (Bilateral Full Scope Treaties)with 68 countries. |
| Pakistan is the world’s fifth most populous country. The country has a predominantly young population, with approximately two-thirds of its population under the age of 30. |
| Around 1,157 foreign companies are currently registered with the Securities and Exchange Commission of Pakistan. |
Ripe for FDI
Alongside mining, Pakistan offers opportunities across several sectors for foreign investors, including technology and digital services, agriculture and agribusiness, infrastructure, logistics and transportation, energy and renewable power, and healthcare.
Translating these opportunities into sustained foreign investment remains a challenge, however. Net FDI fell by 28.4% in the July to May period of 2026 compared with the same period a year earlier. Pakistan received $1.6 billion in net FDI during the period, down from $2.3 billion in the corresponding period of 2025.
China remained the largest source, contributing $819 million, followed by Hong Kong ($308.4 million), the UAE ($219 million), Switzerland ($187 million) and the U.K. ($113 million). The largest sectoral recipients were electricity, gas, steam and air-conditioning supply, which attracted $1.1 billion, and financial and insurance activities, which received $808 million.
The established multinational presence in Pakistan also reflects the depth of its domestic consumer market and their long-term interest in the economy. Unilever, a British multinational company, sells fast-moving consumer goods. Switzerland’s Nestlé SA supplies dairy, infant nutrition, and bottled drinking water. Shell PLC, headquartered in London, distributes petroleum fuels and high-performance lubricants. Abbott Laboratories and PepsiCo Inc., U.S.-based companies, sell pharmaceuticals and beverages, respectively.
Attracting FDI alone, however, will not be sufficient to strengthen Pakistan’s external position. The country needs to expand and diversify its export base to generate sustainable foreign-exchange earnings. Its export base remains highly concentrated in textiles/cotton products and rice. Out of the total exports of $32 billion in 2025, textiles and apparel were the largest sector at about $17.9 billion, or roughly 56% of total exports. As part of Pakistan’s export diversification drive, it is seeking new opportunities for Pakistani rice, textiles, agricultural products, pharmaceuticals, processed food, light engineering goods and services.
Pakistan’s external vulnerability is not only about exports and FDI but also about the source of external financing. China remains Pakistan’s largest bilateral creditor, accounting for around 23% of the country’s $129.7 billion in total outstanding external debt as of 2024. To diversify external financing away from China, Pakistan is seeking a $10 billion fund from the U.S. to strengthen foreign exchange reserves, support the rupee, and reduce dependence on repeated bilateral loan rollovers.
Ultimately, Pakistan’s challenge is to convert macroeconomic stabilization into sustainable growth while reducing its exposure to global shocks, external financing pressures, and domestic security risks.
Rajesh Trichur Venkiteswaran is a contributing writer based in India.